“Wake me up when September ends.” – Green Day
September is living up to its reputation for being fractious, volatile, and generally a down month. While it has felt terrible, and pockets of the market have pulled back sharply, through Monday 9/14, the S&P is off a little under -1%. This is not the Ides of March or Black Monday just yet. However, the wall of worry the market is being asked to climb continues to get higher and steeper. Interest rates and treasury yields are now the biggest risks to the market, and both look like they could break out higher. Historically, policy error is a notorious bull-market killer and this environment is risky.
We are trapped in a doom-loop news cycle that may not get better in the next few weeks. Markets are entering the dead zone for earnings. Q2 is well and truly wrapped up (with a few off-cycle stragglers), and Q3 does not kick off until mid-October. That leaves the market hyper-focused on macro, which, spoiler alert, is rather terrible right now. The two opposing forces driving the market continue to face off with equity fundamentals extremely strong (+25% EPS growth, margin expansion, strong balance sheets) fighting against a very weak macro (geopolitical risk, sticky inflation, higher yields & potentially higher rates). We are also fighting against a significant increase in political noise with the coming election. It becomes harder for investors to focus on the fundamentals when the macro malaise is dominating the news cycle.
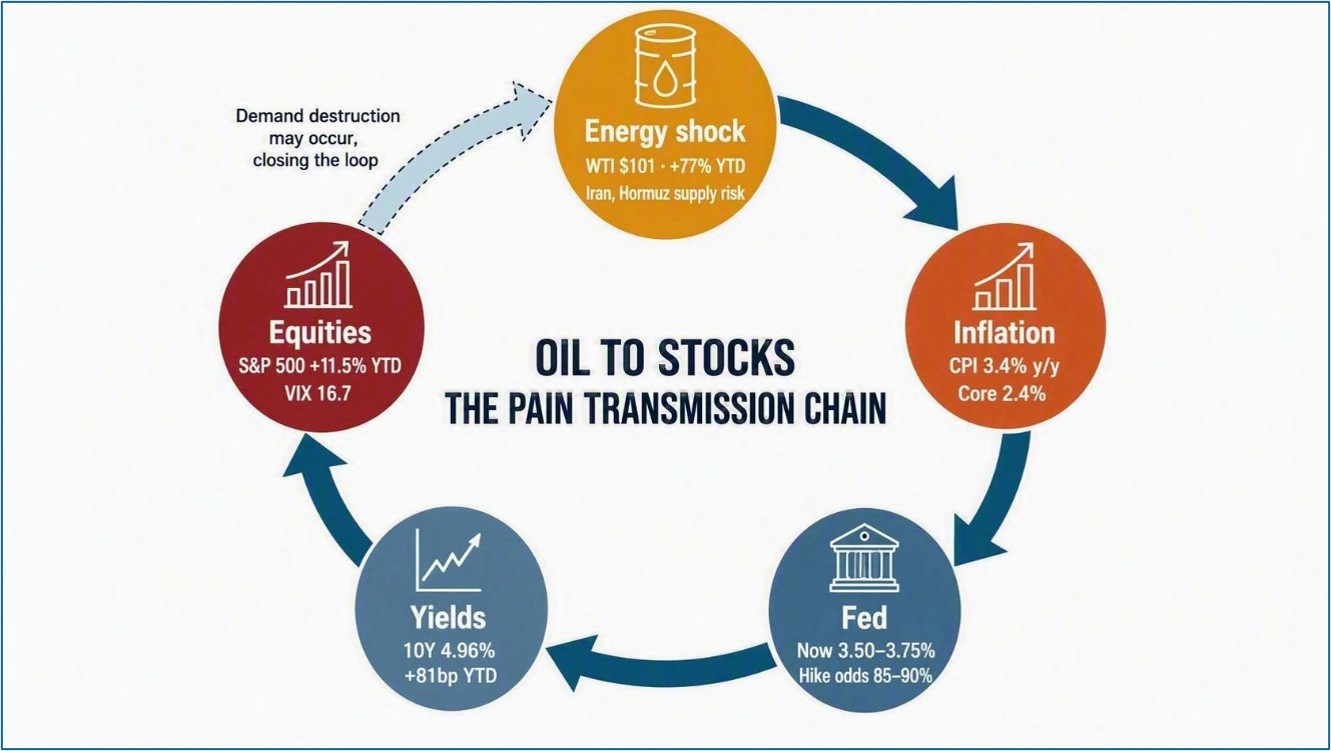
What becomes difficult now is differentiating between a signal, which should be listened to and traded upon, and noise- which is just loud distractions and not a real trend or trade signal. There are legitimate risks to the equity market at this point in the cycle, but there remains a strong fundamental undercurrent and plenty of catalysts as well. We have moved near-term tactically bearish but strategically, longer term bullish. The recent updates from AI leaders warning caution should be watched, as well as if 10-year yields well and truly break higher, and oil prices/Iran risks. Check out our quarterly outlook next week for more on both. But until then, don’t let all the loud noise drown out your investment plan.